

Esta página ha sido redactada, editada, revisada y aprobada por Rubén Davidoff siguiendo nuestro exhaustivo directrices editoriales Ruben Davidoff, El socio fundador cuenta con más de 30 años de experiencia legal como abogado especializado en lesiones personales en Nueva York.
Índice
Settling a personal injury claim with an insurance company in Queens means agreeing on a number, clearing any liens or consents New York law requires, signing a release, and getting paid on time. Each of those steps has rules that can raise or shrink what you actually keep. If an adjuster keeps calling, or an offer is sitting on your kitchen table, it is normal to feel pressure to just make it stop.
Davidoff Law handles each of these steps for injured people and families across Queens so you can focus on getting better.
Call 718-268-8800 for a free case evaluation before you sign anything.
How Davidoff Law Helps Queens Clients Settle With Insurance Companies
An adjuster's offer is only one piece of a settlement. We handle the paperwork and legal steps around it, where small mistakes can cost real money. For Queens clients, our team:
- Sends written requests for the at-fault party's insurance limits
- Tracks the 30-day notice window that protects underinsured motorist coverage
- Requests workers' compensation carrier consent when an injury happened on the job
- Reviews every lien notice before money changes hands
- Tenders the signed release in the way that starts New York's payment deadline
Our main office is in Fresh Meadows at 75-60 188th Street, we are available 24/7, and se habla español. We handle personal injury cases on a contingency fee basis, and we explain how the terms of your agreement apply before you sign it.
Settling a Personal Injury Claim With an Insurance Company in Queens, Step by Step
Every case moves at its own pace, but most Queens settlements follow the same order:
- Open your claims: After a car crash, you generally open a no-fault claim for medical bills and lost earnings, plus a separate injury claim against the at-fault driver's liability insurance.
- Request the insurance limits in writing: Knowing how much coverage exists shapes every number that follows.
- Treat until your doctors understand your injuries: Settling before you know your long-term prognosis can leave future care unpaid.
- Send a demand package: This includes medical records, bills, wage documentation, and a settlement demand.
- Negotiate: Offers and counteroffers often go back and forth several times, so it helps to know how settlement negotiations typically unfold.
- Clear consents and liens: Some carriers must approve the deal, and some benefit providers have a legal right to be repaid.
- Sign the release and get paid: The release ends the claim, and in a pending lawsuit New York sets a deadline for payment.
Which Insurance Company Are You Settling With?
An injury in Queens can involve more than one insurer, and each plays a different role:
- The at-fault party's liability insurer pays for pain and suffering and other losses when the claim settles, up to its policy limits.
- Your no-fault insurer pays basic economic loss, such as medical expenses and part of your lost earnings, up to $50,000 per person under Insurance Law § 5102.
- Your supplementary uninsured/underinsured motorist (SUM) coverage can pay when the at-fault driver has no insurance or too little.
- A homeowner's, landlord's, or business's liability insurer typically handles slip and fall and other premises claims.
- A workers' compensation carrier is involved if you were hurt on the job, and its rights must be addressed before any injury settlement.
How to Get the At-Fault Driver's Policy Limits in Writing
Insurers do not always volunteer how much coverage their customer carries. New York requires liability insurers to disclose bodily injury limits when someone who has filed a claim makes a written request. The Department of Financial Services treats a failure to disclose as an unfair claim settlement practice.
If you carry SUM coverage and share your own coverage limits, the other driver's insurer must disclose its limits within 45 days of your written request. Under a DFS legal opinion on Insurance Law § 3420(f)(2)(A), your time to make a SUM claim is tolled while that insurer fails to disclose.
When Should You Settle a Queens Injury Claim?
The right time to settle is usually when your doctors can describe your long-term outlook and the full cost of your care. Settling earlier trades a faster check for the risk that a later surgery or setback goes unpaid.
Why an Early Release Can Cost You Later
A settlement release is typically written to end your claim for good, even if your condition worsens. Before you consider signing a quick settlement release, make sure future treatment, lost earning capacity, and ongoing pain are part of the number.
New York Deadlines That Shape Settlement Timing
Insurers know the calendar, and a claim loses leverage as deadlines approach. Keep these dates in view:
- Three years to file most personal injury lawsuits under CPLR 214(5)
- 90 days to serve a notice of claim against a public corporation, such as New York City, under General Municipal Law § 50-e
Negotiating with an adjuster does not replace filing a lawsuit or notice of claim on time.
What Will You Actually Take Home From a Settlement Offer?
The number an adjuster offers is not the number you deposit. Liens, fees, case costs, and shared fault can all change your net recovery, which is why we compare every offer against what your Queens personal injury case may be worth.
New York Limits Health Insurer Claims on Your Settlement
Bajo General Obligations Law § 5-335, when you settle an injury claim, whether in a lawsuit or not, the law presumes the settlement does not include medical costs or lost earnings an insurer already paid. That insurer generally has no lien and no right to be repaid from your settlement.
The protection does not reach every payer, including:
- Medicare
- Medicaid
- Workers' compensation insurance
- Certain benefits under New York's no-fault law, including additional first-party benefits
We review every lien notice before you sign, because the type of plan behind it matters.
How Shared Fault Affects Your Settlement in 2026
Bajo CPLR 1411, most New York injury claims still allow a recovery reduced by your share of fault. A 2026 amendment changed that for motor vehicle cases covered by no-fault insurance: if your fault is greater than the defendant's, or greater than all defendants combined, you cannot recover. An even 50/50 split still allows a reduced recovery.
Adjusters often raise fault arguments to lower an offer. That makes the evidence about who caused the crash important during settlement, not just at trial.
Consents You May Need Before Signing a New York Settlement
Some settlements need approval from someone other than you and the insurer. Missing one of these steps can cost you benefits or leave the agreement open to challenge.
Your Underinsured Motorist (SUM) Carrier's 30-Day Window
If the at-fault driver offers the full limits of their policy and you plan to pursue SUM coverage, timing matters. New York's highest court explained in Matter of Central Mutual Insurance Co. (Bemiss) that 30 days after you notify your SUM carrier of a full-limits offer, you may sign the release and keep SUM eligibility. The exception is when the carrier agrees to advance the settlement amount instead.
Signing before that window closes, or without giving notice, can put your SUM benefits at risk.
Workers' Compensation Consent After a Queens Work Injury
If you were hurt on a construction site or another job and also have a claim against a negligent outside party, the workers' compensation carrier's rights come into play. Under Workers' Compensation Law § 29(5), you generally need the carrier's written consent or a court compromise order to settle that claim and keep receiving benefits.
Courts have upheld cutting off future benefits when a worker settled without either one. The carrier may also hold a lien that is repaid from the recovery.
Court Approval When the Injured Person Is a Child
New York does not let a parent simply sign away a child's injury claim. A child's settlement must be approved by a court as fair, reasonable, and in the child's best interests.
CPLR 1208 requires sworn statements from the parent or guardian and the attorney covering the injuries, the settlement terms, and the proposed distribution. The family and attorney attend before the judge unless the court excuses it for good cause. Learn more about bringing a claim on behalf of a child.
Settling With One Insurer When Several Parties Share Fault
When two or more parties caused your injury, a release given to one does not automatically release the others. Under General Obligations Law § 15-108, your claim against the remaining parties is reduced by the greatest of the amount in the release, the amount paid, or the settling party's equitable share of the damages.
For example, suppose you accept a $25,000 policy-limits settlement from one driver who is later found 60% responsible for $200,000 in damages. Your claim against the other driver drops by $120,000, not $25,000.
What Happens After You Sign the Release?
How Long the Insurance Company Has to Pay
When a lawsuit settles, CPLR 5003-a generally requires the defendant to pay within 21 days after you tender a signed release and a stipulation discontinuing the case. Municipalities and public corporations not indemnified by the state get 90 days, and settlements needing court approval also require a copy of the approval order.
Tender means personal delivery or registered or certified mail with a return receipt. If payment is late, you can ask the court to enter a judgment for the settlement amount plus costs, disbursements, and interest from the tender date. These deadlines apply to settled lawsuits, so a claim resolved before suit is filed relies on the terms of the agreement.
How Settlement Funds Are Distributed
Once the check arrives, several things typically happen before you receive your share:
- Liens that legally must be repaid, such as Medicare or workers' compensation, are resolved.
- Attorney fees and case costs are deducted as set out in your signed fee agreement.
- The remaining balance is released to you.
Ask for a written breakdown of every deduction so you can see how your net amount was calculated.
What If the Insurance Company Refuses to Offer a Fair Settlement?
An insurer cannot be forced to settle, but you still have options when talks stall:
- File a lawsuit in Queens: El Supreme Court, Queens County, Civil Term at 88-11 Sutphin Boulevard in Jamaica generally hears higher-value civil cases, while Civil Court in Queens sits at 89-17 Sutphin Blvd.
- Report unfair claim handling: DFS accepts insurance complaints through its online consumer complaint process.
- Challenge a no-fault denial: If your no-fault insurer denies or ignores a claim, DFS notes you can go to court, file a complaint, or request no-fault arbitration.
A filed case brings discovery, depositions, and court deadlines, and preparing for court can change how an insurer values a claim. Learn more about whether your Queens case may go to trial.
Frequently Asked Questions About Settling a Queens Personal Injury Claim With an Insurance Company
How soon must an insurance company pay a settlement in New York?
If your lawsuit is settled, the defendant generally must pay within 21 days after you tender the signed release and stipulation, or 90 days for municipalities and public corporations not indemnified by the state. Settlements reached before a lawsuit follow the payment terms in the agreement.
Will the insurance company tell me the at-fault driver's policy limits?
New York requires liability insurers to disclose bodily injury limits after a written request from someone who has filed a claim. If you have SUM coverage and share your own limits, the other driver's insurer must respond within 45 days.
Should I accept the first settlement offer?
Not before you understand your injuries, your future care, and any liens. A first offer often reflects the insurer's early view of the claim, before your full medical records and losses are documented. Once you sign the release, you generally cannot reopen the claim.
Can my health insurance take part of my settlement?
Usually not. New York law presumes a settlement does not include medical costs an insurer already paid, which generally blocks health insurer liens. Medicare, Medicaid, workers' compensation, and certain no-fault benefits are exceptions.
Do insurance companies prefer to settle out of court?
Many claims resolve without a trial because both sides avoid cost, delay, and uncertainty. An insurer weighs how a Queens jury might view the case, so a well-documented claim can affect its willingness to settle. Every case is different, and some do go to trial.
Talk to Our Queens Personal Injury Lawyer Before You Settle With an Insurance Company
Settling a personal injury claim with an insurance company is a legal transaction, not just a negotiation over a number. Davidoff Law can request the policy limits, protect your SUM and workers' compensation rights, review liens, and handle the release so each step follows New York's rules.
Founder and Managing Attorney Ruben Davidoff and our team serve injured people throughout Queens on a contingency fee basis. Call 718-268-8800 today for a free case evaluation.
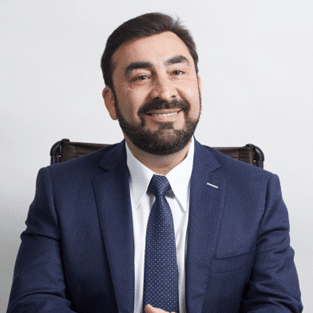
Rubén Davidoff, fundador de Davidoff Law, estableció su despacho en 2012 tras mudarse a Queens en 1988 y comenzar su carrera jurídica en 1997. Admitido en el estado de Nueva York y en el Tribunal de Distrito de los Estados Unidos para el Distrito Este de Nueva York, cuenta con una amplia experiencia en lesiones personales, habiendo llevado diversos casos como accidentes aéreos, accidentes automovilísticos y casos de resbalones, tropiezos y caídas. El Sr. Davidoff ofrece una atención personalizada y ha recuperado millones para sus clientes a través de acuerdos o veredictos, aprovechando sus décadas de experiencia.
