

This page was written, edited, reviewed & approved by Ruben Davidoff following our comprehensive editorial guidelines Ruben Davidoff, the Founding Partner, has 30+ years of legal experience as a New York personal injury attorney.
Table of Contents
Being hit by an uninsured driver does not automatically mean you are left without a way to recover compensation. In New York, your own insurance coverage, other responsible parties, and a direct claim against the driver may still provide options.
Motorcycle cases are different from ordinary car accident claims, however, because riders are generally excluded from New York’s no-fault system. That makes uninsured motorist coverage and a careful review of all available insurance especially important.
Davidoff Law helps injured motorcyclists throughout New York understand their coverage and pursue compensation after serious crashes. Call 718-268-8800 for a free consultation.
Key Takeaways
- An uninsured driver does not automatically eliminate your right to compensation. UM coverage, other insurance policies, responsible third parties, or a direct lawsuit may still provide recovery options.
- Motorcycle riders are generally excluded from New York’s ordinary no-fault benefits. That makes UM, SUM, health insurance, and other sources of coverage especially important.
- UM covers qualifying uninsured-driver claims. SUM includes uninsured protection and may also cover qualifying underinsured-driver claims, subject to policy limits and requirements.
- Insurance deadlines and policy requirements matter. Prompt notice, proof of the other driver’s insurance status, and careful review of your policy can affect whether coverage is available.
Can I Recover If an Uninsured Driver Hit My Motorcycle?
Potentially, yes.
If an uninsured driver caused your motorcycle crash, your own uninsured motorist (UM) coverage may apply. You may also have options through other insurance policies, additional responsible parties, or a lawsuit against the driver.
Why Motorcycle Claims Are Different in New York
The biggest difference is New York’s no-fault system. Under New York Insurance Law § 5103, motorcycle operators and passengers are generally excluded from the first-party no-fault benefits available to many people injured in car crashes.
That means an injured motorcyclist usually cannot rely on standard no-fault coverage to pay medical bills and lost wages after a crash.
This distinction becomes especially important when the at-fault driver has no insurance.
What Is Uninsured Motorist Coverage?
Uninsured motorist coverage is designed to protect you when the person who caused the accident has no applicable liability insurance.
Under Insurance Law § 3420(f), New York automobile policies generally include uninsured motorist protection for bodily injury caused by uninsured vehicles and certain hit-and-run drivers.
Depending on the policy and circumstances, UM coverage may apply when:
- The other driver had no insurance
- The driver’s policy had lapsed
- The insurer denies or disclaims coverage
- The vehicle was stolen or otherwise lacked applicable coverage
- The driver fled and cannot be identified in a qualifying hit-and-run case
A UM claim is generally made through your own insurance company. That does not mean you caused the accident. Your insurer effectively steps into the position of the uninsured driver for purposes of evaluating the claim.
Your insurer may still investigate fault, injuries, damages, and whether the policy requirements were satisfied.
Does My Motorcycle Policy Include Uninsured Motorist Coverage?
New York requires uninsured motorist protection in qualifying motor vehicle liability policies, but the exact coverage available depends on the policy.
Mandatory New York UM coverage generally provides minimum bodily-injury limits of $25,000 per person and $50,000 per accident for nonfatal injuries. Your actual coverage may be higher, so check the declarations page and endorsements.
A household auto policy does not automatically cover your motorcycle crash. An owned-vehicle exclusion may prevent SUM recovery when you were riding a motorcycle you own that is not insured for SUM under that policy.
Important documents may include:
- The declarations page
- UM endorsements
- SUM endorsements
- Policy exclusions
- Coverage limits
- Notice provisions
Motorcycle policies and automobile policies can contain different terms, and questions about who qualifies as an insured may depend on the wording of the contract. That is why the actual policy should be reviewed rather than relying only on what appears on an insurance card.
UM vs. SUM Coverage
UM and SUM coverage address different insurance problems. The main difference is whether the at-fault driver has no applicable insurance or not enough insurance.
| UM Coverage | SUM Coverage | |
| What it means | Uninsured motorist coverage | Supplementary uninsured/underinsured motorist coverage |
| When it may apply | The at-fault driver has no applicable bodily injury insurance | The at-fault driver has insurance, but the available limits are too low |
| Common situations | Uninsured driver, qualifying hit-and-run, or certain coverage denials | Serious injuries where the other driver's liability limits do not provide enough coverage |
| Where the claim is made | Generally through your own applicable insurance coverage | Generally through your own applicable SUM coverage after addressing the at-fault driver's policy |
| Important consideration | Coverage limits and policy requirements still apply | Notice, consent, settlement, and policy-limit requirements may apply |
For example, if the other driver’s applicable liability limits are lower than the relevant limits under your policy, SUM may provide additional compensation. Payments from liable parties generally reduce the amount available under SUM.
Before settling with an underinsured driver, however, your policy should be reviewed carefully. SUM coverage may contain notice, consent, and settlement requirements that can affect your ability to pursue additional benefits.
Hit-and-Run Motorcycle Claims
A hit-and-run vehicle may qualify as an uninsured vehicle for purposes of UM coverage. However, Insurance Law § 3420(f)(3) generally requires physical contact in many claims involving an unidentified vehicle.
For example, if a vehicle strikes your motorcycle and then leaves the scene, UM coverage may potentially apply. A claim can become more complicated when a vehicle forces a motorcyclist off the road without actually making contact.
Hit-and-run crashes should also be reported promptly, and evidence should be preserved whenever possible. Useful evidence may include:
- Police reports
- Surveillance video
- Dashcam footage
- Witness statements
- Photos of vehicle or motorcycle damage
- Debris from the scene
- Descriptions of the fleeing vehicle
The sooner that evidence is identified, the better the chance of determining what happened and whether coverage applies.
Can I Sue the Uninsured Driver Directly?
Yes. An uninsured driver can still be legally responsible for causing a motorcycle accident.
A personal injury lawsuit may seek compensation for losses such as:
- Medical expenses
- Lost income
- Reduced earning capacity
- Pain and suffering
- Other damages supported by the case
The practical problem is collectability.
A person may be legally responsible for a large judgment but have few assets or limited income available to satisfy it. For that reason, identifying insurance coverage and other responsible parties can be just as important as proving that the uninsured driver caused the crash.
A direct lawsuit may still be worthwhile in some cases, but the likely sources of recovery should be evaluated early.
Can MVAIC Help After an Uninsured Motorcycle Crash?
Possibly, but this area is more limited for motorcycle riders than for many other accident victims.
The Motor Vehicle Accident Indemnification Corporation (MVAIC) can provide a potential source of compensation in certain crashes involving uninsured or unidentified vehicles when no other applicable insurance is available.
However, motorcycle occupants are generally excluded from New York’s ordinary no-fault benefits. That means you should not assume MVAIC will cover the same medical expenses and lost wages that might be available to someone injured in a passenger vehicle.
Whether MVAIC can help depends on the facts, your insurance status, the vehicle involved, and the type of claim being pursued.
Who Pays My Medical Bills If No-Fault Does Not Apply?
Because motorcyclists are generally excluded from New York no-fault benefits, medical expenses may need to be handled through other sources.
Depending on the circumstances, these may include:
- Health insurance
- A direct claim against the negligent driver
- Workers’ compensation if the crash happened during qualifying employment
- Claims against other responsible parties
Keep copies of medical bills, insurance statements, receipts, and records showing lost income. These documents can help establish the financial losses connected to the crash.
What Other Parties May Be Responsible?
An uninsured driver may not be the only person or company legally responsible for the accident.
Depending on how the crash happened, other potentially liable parties may include:
- The vehicle owner
- The driver’s employer
- A commercial company
- A contractor
- A maintenance provider
- A government entity responsible for a dangerous roadway condition
For example, if an uninsured driver was working at the time of the crash, an employer may potentially share responsibility depending on the facts. Identifying every possible defendant can be especially important when the person who caused the crash has no insurance or limited assets.
What If the Driver Had Insurance, but the Carrier Denied Coverage?
A denied or disclaimed policy can sometimes create an uninsured motorist issue.
For example, an insurer may deny coverage because:
- The policy had been canceled
- The driver was excluded
- The vehicle was not covered
- The insurer claims a policy condition was violated
Insurance Law § 3420 addresses certain circumstances in which an uninsured motorist claim may arise after coverage is denied or disclaimed. A denial letter should be reviewed carefully. The fact that one insurer refuses to pay does not necessarily mean there are no other coverage options.
How Soon Do I Need to Notify My Insurance Company?
Notify your insurer as soon as reasonably possible after learning that the other driver may be uninsured or underinsured.
UM and SUM policies contain their own notice and claim requirements. These can be much shorter than the general deadline for filing a personal injury lawsuit. The exact deadline depends on the policy and circumstances, so there is no single notice period that applies to every motorcycle claim.
Prompt notice also gives the insurer an opportunity to investigate the crash, confirm coverage, and preserve evidence. Waiting too long can create unnecessary disputes over whether policy conditions were satisfied.
Steps to Take After Learning the Driver Was Uninsured
A few practical steps can help protect the claim:
- Get the police report: Confirm the driver and vehicle information recorded after the crash.
- Verify the insurance status: A driver saying they are uninsured does not always establish the full coverage picture.
- Notify your insurer promptly: Report the possibility of a UM or SUM claim.
- Preserve evidence: Keep photographs, videos, witness information, repair records, and medical documentation.
- Request the policy documents: The declarations page and UM/SUM endorsements can show what coverage may apply.
- Document financial losses: Keep proof of medical costs, missed work, and other expenses.
- Avoid signing releases too quickly: A settlement involving another policy may affect SUM rights.
- Review all potential defendants: The uninsured driver may not be the only source of recovery.
Can My Own Insurance Company Dispute My UM or SUM Claim?
Yes. Even though UM or SUM coverage comes from your own policy, the insurer may still dispute:
- Who caused the accident
- Whether the other vehicle was uninsured or underinsured
- Whether you qualify as an insured
- Whether the claim was reported properly
- The severity of your injuries
- The amount of your damages
- Whether policy conditions were satisfied
Some UM and SUM disputes are resolved through arbitration rather than an ordinary lawsuit against the insurer. That is another reason to review the policy carefully instead of assuming your own carrier will automatically pay the claim.
When Should I Contact an NYC Motorcycle Accident Lawyer?
Consider speaking with an attorney if the other driver has no insurance, their carrier denies coverage, the driver fled, your insurer disputes UM or SUM coverage, or your injuries are serious.
A lawyer can review the available policies, identify other potentially liable parties, preserve evidence, and determine which claims may be available.
Davidoff Law represents injured motorcyclists throughout New York City. Call 718-268-8800 for a free consultation.
FAQs About Uninsured Drivers and Motorcycle Accidents
Potentially. UM coverage, other insurance policies, responsible third parties, or a direct lawsuit may provide options depending on the facts.
Generally, no. Motorcycle operators and passengers are generally excluded from ordinary first-party no-fault benefits in New York.
SUM coverage may provide additional compensation when the at-fault driver’s bodily injury limits are too low, subject to your own policy terms and limits.
Potentially. Qualifying hit-and-run crashes may fall under UM coverage, although New York imposes specific requirements, including physical contact in many unidentified-vehicle claims.
An Uninsured Driver Does Not Always Mean an Uninsured Claim
A motorcycle crash involving an uninsured driver can make recovery more complicated, but it does not automatically eliminate your options. UM or SUM coverage, other responsible parties, health insurance, and direct claims may all become important.
Davidoff Law can evaluate your motorcycle accident claim and identify potential sources of compensation. Call 718-268-8800 for a free consultation.
Davidoff Law Personal Injury Lawyers
- 75-60 188th Street, Fresh Meadows, NY 11366
- (718) 900-0000
Davidoff Law Personal Injury Lawyers - New York City
- 60 E 42nd Street, Suite 1720, New York, NY 10165
- (212) 900-0000
APPOINTMENT ONLY
Davidoff Law Personal Injury Lawyers - Bronx
- 2322 Arthur Ave, 207, Bronx, NY 10458
- (516) 830-0956
Queens Personal Injury Lawyer Ruben Davidoff
- 108-18 Queens Blvd., Suite 404, Queens NY 11375
- (718) 268-8800
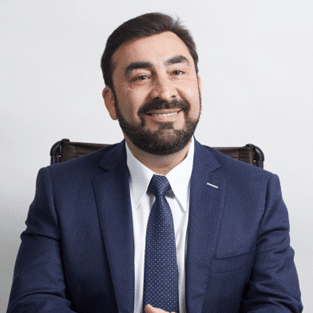
Ruben Davidoff, founder of Davidoff Law, established his practice in 2012 after moving to Queens in 1988 and beginning his legal career in 1997. Admitted in NY State and the US District Court for the Eastern District of NY, he has extensive experience in personal injury, handling various cases like airline crashes, auto accidents, and slip/trip and fall cases. Mr. Davidoff provides personalized attention, recovering millions for clients through settlements or verdicts, leveraging decades of experience.


