

This page was written, edited, reviewed & approved by Ruben Davidoff following our comprehensive editorial guidelines Ruben Davidoff, the Founding Partner, has 30+ years of legal experience as a New York personal injury attorney.
Table of Contents
In most cases, no, not the first offer, and not until you know your claim's full value and what you would actually keep. If you are asking yourself, "Should I accept a settlement offer from the insurance company?" pausing to ask is the right instinct. Adjusters often call while you are still in treatment, missing work, and watching bills pile up.
Once you sign a release, your claim generally ends, even if your injuries prove worse than expected. Davidoff Law reviews insurance offers for injured people across New York City, including the coverage behind each offer and the state rules that shape what you take home.
Call 718-268-8800 to talk with our team before you sign.
Should I Accept a Settlement Offer from the Insurance Company in New York?
Not until three questions have clear answers. First, has your treatment progressed far enough for your doctors to describe your long-term outlook? Second, has every source of coverage been identified, including other responsible parties and your own policy?
Third, what would you actually net after liens, fees, and costs are paid? If any answer is unclear, accepting now means guessing about money you cannot ask for later. The first settlement offer is often an opening position rather than a final assessment of your claim.
Accepting almost always means signing a release that closes the claim for good. Before you put your name on one, learn what signing a settlement release means for your rights.
How to Tell Whether an Insurance Settlement Offer Is Fair
A fair offer accounts for your past losses, your future needs, and the legal rules that apply to your claim. Each of the following checks helps you compare the number on the page to the claim behind it.
Measure the Offer Against Every Category of Loss
Start with what the injury has cost you so far, then estimate what it will cost going forward. Economic losses include medical treatment, lost wages, and reduced earning capacity. Non-economic losses include pain and suffering, limits on daily activities, and emotional harm.
Future losses are easy to overlook in an early offer because they depend on a prognosis that may not exist yet. For a closer look at valuation, see what your personal injury case may be worth in New York.
Check Whether Your Injury Meets New York's Serious Injury Threshold
In car crash cases, New York's no-fault system pays basic economic loss, such as medical bills and some lost earnings, up to $50,000 per person. To recover pain and suffering from the at-fault driver, your injury generally must qualify as a serious injury under Insurance Law § 5102(d). The categories now include the following:
- Death
- Dismemberment
- Significant disfigurement
- A fracture
- Loss of a fetus
- Permanent loss of use of a body organ, member, function, or system
- Permanent consequential limitation of use of a body organ or member
- Significant limitation of use of a body function or system
An adjuster who believes your injury falls short of this threshold may offer little or nothing for pain and suffering. Medical records that document your injury in these terms can change that conversation.
Work Out What You Would Actually Take Home
The number in the offer is not the number you keep. Statutory liens, attorney's fees if you hire counsel, and case costs can all come out of the gross amount.
A $40,000 offer can look reasonable until a lien and unpaid medical balances leave far less for your recovery. Before you accept, ask for a written breakdown of every deduction.
Know What New York Requires of the Insurance Company
Insurance Law § 2601 prohibits insurers from engaging in unfair claim settlement practices as a general business practice. One listed practice is failing to attempt in good faith to make prompt, fair, and equitable settlements once liability has become reasonably clear. Another is pushing policyholders into lawsuits by offering substantially less than they later recover in court.
After receiving a properly executed proof of loss, an insurer must say whether it accepts or denies the claim within 30 working days. The Department of Financial Services can impose monetary penalties for violations. If an insurer stalls or ignores you, you can file a complaint with the Department of Financial Services.
How New York's 2026 Auto Insurance Reforms Affect Crash Settlement Offers
New York changed key rules for motor vehicle injury cases in 2026. According to the Department of Financial Services, the amendments took effect on May 26, 2026, and apply to actions commenced on or after that date. They can change how an insurer values a crash claim:
- The serious injury definition no longer includes the 90/180-day category for non-permanent injuries that kept a person from usual daily activities.
- The judge or jury deciding the case must determine who was at fault before deciding whether an injury qualifies as serious.
- In a case subject to the no-fault law, an injured person whose fault is greater than the fault of the defendant, or of all defendants combined, cannot recover.
- A $100,000 cap on non-economic damages applies to certain at-fault injured drivers. It covers drivers of an uninsured vehicle they were responsible for insuring, and drivers later convicted of impaired driving or of a felony committed while driving, but not cases involving death.
These changes give insurers new arguments to reduce offers, especially when fault is disputed. Claims outside the no-fault system, such as many fall and premises cases, still follow CPLR 1411. Under that rule, your share of fault reduces your damages without barring recovery.
New York Rules That Can Make Accepting an Offer a Costly Mistake
Some of the most expensive settlement mistakes have nothing to do with the dollar amount. They happen when someone signs before handling a rule that protects other money they may be able to pursue.
Underinsured Motorist (SUM) Coverage and the 30-Day Notice Rule
If the at-fault driver's policy is too small to cover your losses, your own supplementary uninsured/underinsured motorist (SUM) coverage may help. SUM endorsements generally require your insurer's consent before you release the at-fault driver.
Under New York's regulation, you can give your insurer written notice of an offer for the other driver's full policy limits. Your insurer then has 30 days to consent or to advance that amount and take over the case.
Settling With One At-Fault Party When Others Share the Blame
Many crashes and falls involve more than one responsible party, such as two drivers or a property owner and a contractor. Under General Obligations Law § 15-108, releasing one party does not automatically release the others. It does reduce your claim against the remaining parties by the greatest of the amount stated in the release, the amount paid, or the released party's equitable share of the damages.
That last option matters. If you settle cheaply with a party a jury later finds heavily at fault, the remaining defendants can receive credit for that party's full share.
Liens That Come Out of Your Settlement
New York gives injured people strong protection against private health insurer reimbursement. Under General Obligations Law § 5-335, a personal injury settlement is conclusively presumed not to include medical costs or lost earnings an insurer paid. That insurer generally has no lien on your settlement.
The protection has exceptions. The following benefits can still carry repayment rights:
- Medicare benefits
- Medicaid benefits
- Workers' compensation benefits
- Additional first-party benefits under New York's no-fault law
Knowing which liens apply, and in what amount, is the only reliable way to measure what an offer leaves you.
Workplace Injuries and the Workers' Compensation Carrier's Consent
If you were hurt on the job and are pursuing a claim against someone other than your employer, the workers' compensation carrier has a lien on that recovery. Under Workers' Compensation Law § 29(5), settling the third-party case generally requires the carrier's written consent or a compromise order from the court. New York courts have barred further benefits when injured workers settled without either one.
A court can approve a compromise within 3 months after the settlement. Approval after that window requires more, including a showing that the delay was not your fault and that the carrier was not prejudiced.
Offers for an Injured Child Need a Judge's Approval
Parents cannot finalize a child's injury settlement on their own. Under CPLR 1207 and 1208, a court must approve the settlement of a child's claim as fair, reasonable, and in the child's best interests. A child's settlement that does not comply with CPLR 1208 generally is not binding.
That means an insurer's check for your child's injuries cannot become final through a simple release. Learn more about bringing a personal injury claim on behalf of a child in New York City.
What to Do Before You Respond to the Adjuster's Offer
A careful response protects your options while negotiation continues. Before you answer the adjuster, take the following steps:
- Ask for the offer in writing: A written offer shows the exact amount, who is paying, and what the insurer expects you to sign. Avoid agreeing to anything over the phone.
- Do not sign or deposit anything yet: Checks and claim forms can carry release language that ends your claim.
- Identify every source of coverage: This includes the at-fault party's policy limits, any other responsible parties, and your own SUM coverage.
- Request lien and benefit information: Ask Medicare, Medicaid, your no-fault insurer, or a workers' compensation carrier for the amounts they paid, as each applies.
- Get your doctor's view of your future care: A documented prognosis helps show costs that have not happened yet.
- Confirm your deadline: Most New York personal injury lawsuits must be filed within 3 years under CPLR 214(5). Claims against the City or another public corporation generally require a notice of claim within 90 days under General Municipal Law § 50-e.
- Respond with a documented counteroffer: A counteroffer backed by records and a clear damages figure gives the adjuster a reason to move. Read more about how settlement negotiation works.
What Happens to Settlement Offers After a Lawsuit Is Filed?
Filing a lawsuit does not end negotiation. Settlement talks often continue through discovery and up to trial, and New York law adds tools that affect both sides.
Formal Offers to Compromise Under CPLR 3221
Under CPLR 3221, a defendant can serve a written offer to allow judgment for a specific amount up to 10 days before trial. You then have 10 days to accept it in writing. If you reject the offer and do not obtain a more favorable judgment, you cannot recover costs from the time of the offer and must pay the defendant's costs from that point.
The jury never learns about the offer. Even so, a formal offer to compromise calls for careful review with your attorney because it shifts cost risk onto you.
How Quickly the Insurer Must Pay Once You Settle
CPLR 5003-a sets payment deadlines once a lawsuit settles. Most settling defendants must pay within 21 days after you tender a signed release and a stipulation discontinuing the action. Tender means personal delivery or registered or certified mail with a return receipt.
A municipality or other public corporation that the state does not indemnify generally has 90 days. When a settlement needs court approval, such as a child's settlement, the approval order must accompany those papers. If payment is late, you may enter judgment for the settlement amount plus costs, disbursements, and interest from the date you tendered the papers.
When Accepting an Insurance Settlement Offer May Make Sense
Accepting is not always a mistake. An offer may be worth serious consideration when the following conditions are true:
- Your doctor has released you from care, and you do not expect future treatment
- The offer accounts for your lost income and out-of-pocket costs
- Every responsible party and insurance policy has been identified
- SUM notice, workers' compensation consent, and court approval have been handled where they apply
- Liens are confirmed, and the amount you would net is clear
Even then, weigh the offer against what a jury could reasonably award and against the time and risk of litigation. Sometimes an offer reflects fair value, and accepting it lets you move forward.
How Davidoff Law Helps New Yorkers Evaluate Insurance Settlement Offers
At Davidoff Law, we look at an offer the way the insurance company does, then add the New York rules an adjuster may leave out. Our attorneys review the offer, identify every available policy, request lien amounts, and calculate what you would net.
When the law requires it, we send SUM notices, seek workers' compensation consent, and file for court approval of a child's settlement. If the insurer will not make a reasonable offer, we can file a lawsuit and continue negotiating as the case moves forward.
Results our firm has obtained include $10 million in a motor vehicle wrongful death case, $5 million in a trip-and-fall case, and $2.5 million in a rear-end collision case. Past results do not guarantee a similar outcome.
We handle personal injury cases on a contingency fee basis, answer calls 24/7, and serve clients in Spanish. Our offices are in Fresh Meadows, Manhattan, and the Bronx, and we represent injured people throughout all five boroughs.
Talk to Our New York City Personal Injury Lawyer Before You Accept an Insurance Settlement Offer
Before you decide whether you should accept a settlement offer from the insurance company, let us review it. Davidoff Law can examine your offer, the coverage behind it, and the New York rules that affect what you would keep.
Founder and Managing Attorney Ruben Davidoff and our team help injured people across New York City, and every case starts with a free case evaluation. Call 718-268-8800 or contact us online to discuss your options.
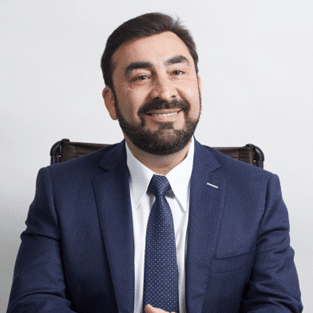
Ruben Davidoff, founder of Davidoff Law, established his practice in 2012 after moving to Queens in 1988 and beginning his legal career in 1997. Admitted in NY State and the US District Court for the Eastern District of NY, he has extensive experience in personal injury, handling various cases like airline crashes, auto accidents, and slip/trip and fall cases. Mr. Davidoff provides personalized attention, recovering millions for clients through settlements or verdicts, leveraging decades of experience.
